The latest Cambodia Real Estate Highlights H1 2025 report from Knight Frank Cambodia indicates that the real estate sector has shown strength and opportunities despite the challenges experienced in the first half of the year; namely tariffs, economic uncertainty and the dispute with Thailand.
The bi-annual report (this week we focus on Phnom Penh) provides a comprehensive overview of the real estate and property across the Office, Retail, Hotel, Condo, Serviced Apartments, Landed Housing and Industrial subsectors. We have selected a handful of interesting data points, but the entire report is worth reading to appreciate the scope of the trends in the property and real estate sectors.
Ross Wheble, Country Head at Knight Frank Cambodia, commented, “What started as a promising year has turned into one of caution. Nevertheless, as the saying goes, every cloud has a silver lining, and the market uncertainty has also brought opportunity.”
Tom O’Sullivan, CEO of realestatecom.kh said, "Knight Frank is right to highlight the challenges, to continue to identify the long-term positive outlook, we’re seeing a market that’s maturing and becoming more selective.
Tougher conditions and oversupply are pushing out weaker developers, creating a healthy flight to quality. Buyers are comparing projects and relying on trusted, licensed agents, with a focus on developers who deliver quality and long-term value. At the same time, stronger regulation is adding transparency, which will support a more sustainable market and encourage greater foreign investment."
The Cambodian government also continued to support the real estate sector with extended tax exemptions and incentives, creating an attractive investment climate.
You can read more insights into the Investment & Market Analysis - Cambodia Condominium Report’s Webinar.
Economic Headwinds Impact Cambodian Market Sentiment
The revised Cambodian economic growth forecast of 4 per cent in 2025 still represents strong growth for the Kingdom, and Ly Hakim, head of research at Knight Frank Cambodia, said: “The Cambodian real estate sector recorded its strongest performance during Q1 2025 since the Covid-19 pandemic.
However, the optimism was short-lived as the Trump Administration announced heavy trade tariffs for the APAC region in April, including Cambodia. This was further compounded by the closure of the Cambodia-Thailand border in May. Whilst the tariffs and ongoing border tensions will continue to weigh down on market sentiment over the short-term, the medium and long-term fundamentals for Cambodia will offer abundant opportunities across all sectors and markets.”
He added, “Despite global challenges, Cambodia’s real estate sector showed strong resilience in early 2025.”
The future economic outlook and main challenges remain:
- Tariffs could affect key trading nations in North America, Europe, and Asia and may accelerate the localisation of supply chains in the U.S
- Ongoing discussions between Thailand and Cambodia have posed challenges for businesses operating in both countries.
Phnom Penh Serviced Apartment Sector H1 2025

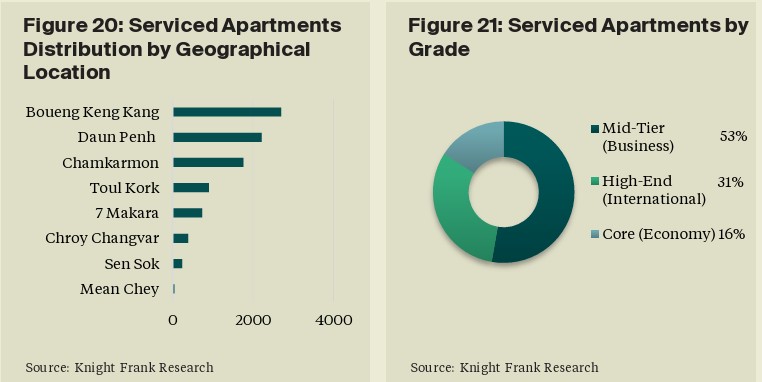
The capital’s serviced apartment sector was stable but is expected to face more challenges in the second half of 2025. The supply reached approximately 8,975 units, which was an increase of 7% compared to 2024.
- Boueng Keng Kang (BKK) once again was the most in-demand district in Phnom Penh, with nearly one-third of the total serviced apartments market.
- Approximately half of the market consists of business-class apartments.
- The number of serviced apartments in Phnom Penh is set to increase and is expected to reach approximately 10,554 by 2028.
Condo Sector in Phnom Penh H1 2025
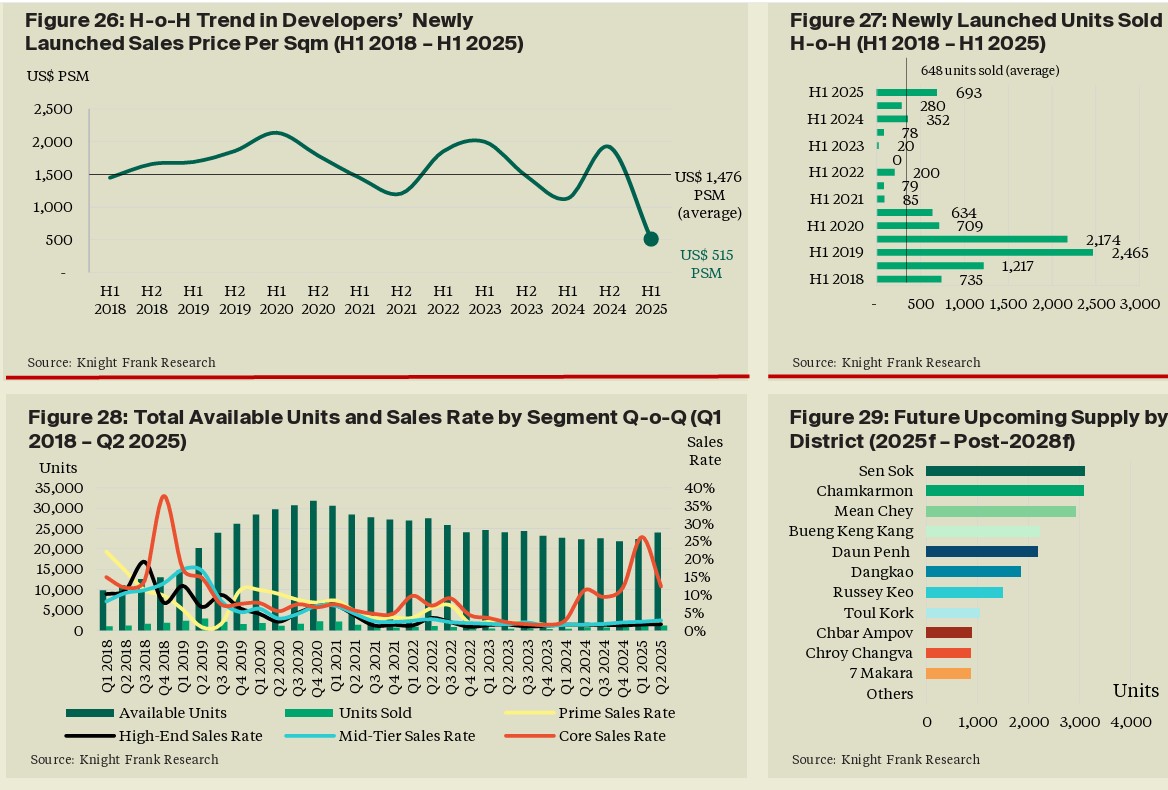
There were positive sales rates to both foreign and domestic buyers in the first half of 2025, but there is expected to be market moderation in the second half of the year due to the ongoing Cambodia-Thailand conflict.
The improvement in the sales was driven by real demand and a combination of “developers' improved understanding and strategies” which included favourable payment terms - these are all points we have raised over the recent year/s.
As realestate.com.kh has also been suggesting, local buyers have become more actively engaged in the market than ever before. The market shift sees a lower reliance on foreign buyers and the availability of more affordable pricing as part of the broader market correction.
- The supply of condominiums reached 61,564 units.
- The number of units sold during H1 2025 was the highest since 2020.
- Chamkarmon, Sen Sok and Mean Chey account for the majority of the future condo supply in the capital.
As for the landed property segment, it continued to see weak overall sales performances and fewer projects launched in the capital.
Phnom Penh Office Sector H1 2025
Knight Frank’s report suggested Phnom Penh’s office sector experienced steady growth amid increased supply and changing market dynamics in the first half of 2025.
The cumulative Phnom Penh office property supply reached 1,015,380 square metres and is expected to grow to 1,557,098 sqm by 2028.
- Grade B office space made up almost half of the market (49%) - This is a year-on-year increase of 5 per cent.
- Centrally-owned buildings accounted for nearly three-quarters of the total office segment market. In Phnom Penh,
- Chamkarmon and Daun Penh contributed the majority of this.
Prime office rents remained stable during H1 2025, and the average prime net effective rent was US$21 per sqm per month.
The report adds that “While the short-term outlook for the Phnom Penh office sector is challenged by rising vacancy rates, the long-term prospects will be shaped by broader economic conditions and external factors.”
It also suggests that newer developments which offer health & wellness spaces, sports/gym facilities could provide unique selling points to differentiate from the competition.
Phnom Penh Retail Sector H1 2025
Retail occupancy dropped slightly year-on-year in the first half of the year, and the decline indicates an increasing challenge in the market, driven by changing consumer behaviours and a short-term oversupply.
- The retail sector in Phnom Penh only saw one project added to the existing supply during H1 2025.
- The total retail supply was recorded at 873,201 sqm of NLA (net leasable area)
- The total supply is expected to increase to 1,147,955 sqm of NLA over the coming years.
- Retail space is concentrated within Sen Sok (31%) and Meanchey District (23%).
- Food and Beverage continued to dominate the tenant mix in Phnom Penh’s shopping centres.
Additional Reading: How Urbanisation is Transforming Cambodia's Real Estate
Phnom Penh’s Hotel Property Sector 2025
Phnom Penh’s hotel accommodation stands at 16,372 rooms, which represents a 6% increase from 2024. Only one internationally branded hotel and a new domestic brand under Morgan Group added 400 rooms to the supply in H1 2025.
Daun Penh has the highest concentration of hotels, with 39% of the total hotel market.
The total hotel supply is expected to reach approximately 19,483 rooms by 2028, with a number of international brands under development.
Find out about DoubleDragon's Hotel101 entering the Cambodian market with developments in Phnom Penh and Sihanoukville.
Industrial Property Sector & SEZ
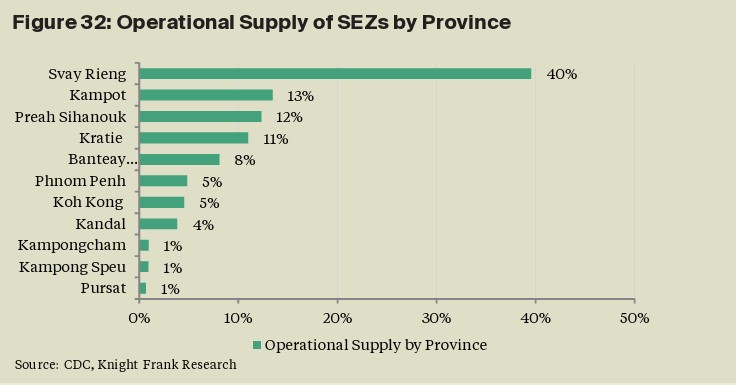
This segment is undergoing a major change as there is a shift from traditional industrial output in “low-end garment production to higher-value industries like electronics, automotive components, and light manufacturing.”
The industrial sector in Cambodia is expected to play a key role in the national growth, and this year is projected to contribute about 34% of the country's GDP. The Special Economic Zones (SEZ) are a key cog in this economic shift.
- Council for the Development of Cambodia (CDC) approved 290 new investment projects, totalling about $4.2 billion, in the first five months of 2025
- 121 out of the newly approved projects were established in Special Economic Zones.
- A total of 28 SEZs are operational, and 32 are still under construction and are yet to be operational.
Next week, we will look at the report’s updates outside of the capital, notably in Siem Reap and Sihanoukville, which are at different points in their own development in Cambodia. Knight Frank points to Sihanoukville as one to watch as it continues to rise as a future gateway city, driven by infrastructure and port development.